
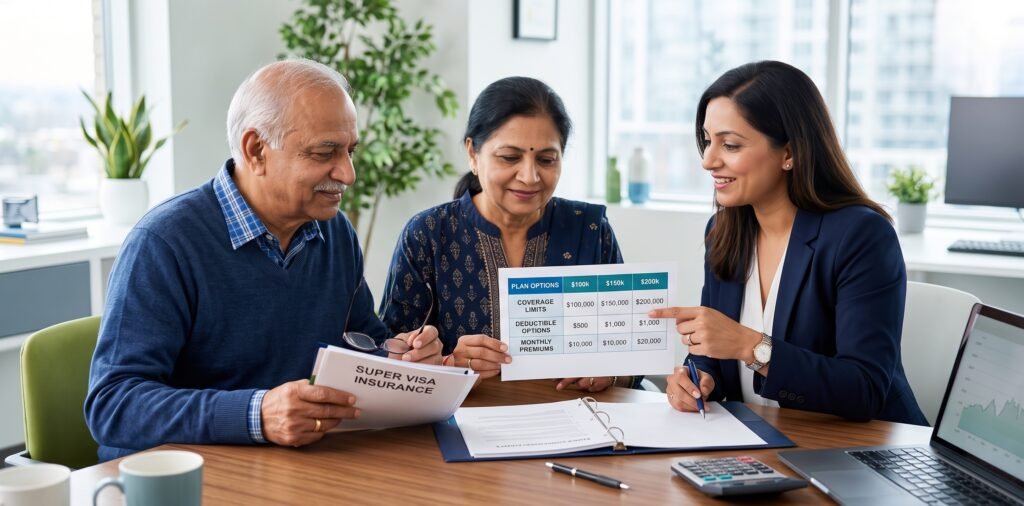
Super visa insurance coverage limits decide how much your insurer will pay if your parents need medical care in Canada. You’re comparing Super Visa insurance quotes. One broker recommends $100,000 coverage with a $500 deductible. Another suggests $150,000 with $1,000. A third offers $200,000 with no deductible.
Your first question: “What’s the difference? Do I really need all that coverage?”
Your second question: “What’s a deductible, and why does it matter?”
Your third question: “How much is this going to cost?”
Here’s the reality: Most families don’t understand the difference between coverage limits and deductibles, so they either overpay for more protection than they need, or underpay and get a plan that leaves them exposed.
Let me walk you through exactly what coverage limits and deductibles actually mean, show you real pricing examples, and help you understand which combination is right for your parents’ situation.
Part 1: Understanding Super Visa Insurance Coverage Limits ($100k vs $150k vs $200k)
Your coverage limit is the maximum amount the insurance company will pay for your medical expenses while you’re in Canada.
Let’s say your parents get hospitalized for pneumonia. The total bill is $50,000.
- If your coverage limit is $100,000 → Insurance pays the full $50,000 (you’re covered)
- If your coverage limit is $50,000 → Insurance pays only $50,000, but then you hit your limit
- If your coverage limit is $25,000 → You pay $25,000 out of pocket; insurance covers only $25,000
The coverage limit is your safety net. Once you exceed it, you’re paying the rest yourself.
How Much Coverage Do You Actually Need?
IRCC requires a minimum of $100,000 for Super Visa. But that doesn’t mean $100,000 is enough—it’s just the legal minimum.
Here’s the truth: Medical expenses in Canada are expensive.
Real Costs in Canada
- Emergency room visit: $500–$2,000
- Hospital stay (1 night): $1,000–$5,000
- Surgery (without complications): $10,000–$40,000
- ICU stay (per day): $5,000–$10,000
- Major surgery with complications: $50,000–$150,000+
- Air ambulance/medical evacuation: $15,000–$50,000
Real example:
Your dad has a heart attack. He’s hospitalized for 5 days, gets an angiogram, spends 2 days in ICU, and is discharged. Total bill: $120,000.
- With $100,000 coverage → You pay $20,000 out of pocket
- With $150,000 coverage → Insurance covers it all
- With $200,000 coverage → You’re protected even if complications arise
See the difference? A $50,000 increase in coverage might cost you $15–20/month more, but it saves you from a $20,000+ emergency bill.
The Three Coverage Options Explained
$100,000 Coverage (Legal Minimum)
- ✅ Meets IRCC requirement
- ✅ Covers most common emergencies (ER visits, minor surgeries, hospital stays)
- ❌ Exposed if major surgery or serious condition occurs
- ❌ No buffer for complications
- Best for: Parents with excellent health, short visits (under 3 months), no pre-existing conditions
$150,000 Coverage (Sweet Spot)
- ✅ Covers most scenarios (hospitalization, surgery, complications)
- ✅ Provides buffer for unexpected issues
- ✅ Recommended by most doctors
- ✅ Only $10–20/month more than $100k
- ❌ Might be insufficient for major surgery + ICU
- Best for: Most families; safe middle ground
$200,000 Coverage (Maximum Protection)
- ✅ Covers major surgery, ICU stays, and complications
- ✅ Peace of mind for longer visits (6–12 months)
- ✅ Protects against worst-case scenarios
- ❌ Most expensive option
- ❌ Probably more than you need (unless parents are very ill)
- Best for: Parents with serious pre-existing conditions, long visits, or medical concerns
Part 2: Understanding Deductibles ($500, $1,000, $2,500, or Higher)
A deductible is the amount YOU pay out of pocket before insurance kicks in.
Example:
You have a $500 deductible. Your dad goes to the ER for chest pain. The bill is $3,000.
- You pay: $500 (your deductible)
- Insurance pays: $2,500
If he goes back to the hospital the next week for a follow-up, and the bill is $2,000:
- You pay: $0 (you already hit your deductible this year)
- Insurance pays: $2,000 (full amount)
Key point: You only pay the deductible once per year, not every visit.
How Deductibles Affect Your Premium
Here’s the trade-off:
- Lower deductible ($500) → Higher monthly premium ($120/month)
- Higher deductible ($1,000–$2,500) → Lower monthly premium ($100/month)
Which should you choose?
Choose Lower Deductible ($500) if:
- ✅ Your parents are likely to use healthcare (pre-existing conditions)
- ✅ You want predictable costs
- ✅ You can’t afford a big out-of-pocket expense
- ✅ Peace of mind matters more than saving $20/month
Choose Higher Deductible ($1,000+) if:
- ✅ Your parents are very healthy
- ✅ You’re willing to risk paying more out of pocket in an emergency
- ✅ You want to save money on premiums
- ✅ Short visit (1–2 months) and low chance of using healthcare
Real comparison:
- $150k coverage + $500 deductible = $125/month (total: $1,500/year)
- $150k coverage + $1,000 deductible = $105/month (total: $1,260/year)
- Savings: $240/year, but you risk paying an extra $500 if they need care
Is $240/year savings worth risking a $500+ emergency expense? Usually not—especially with parents.
Part 3: How Coverage & Deductible Work Together (Real Scenarios)
This is where it gets practical. Let me show you three real situations:
Scenario 1: Healthy Parents, Short Visit
Parents: Dad (72, healthy), Mom (70, healthy) | Visit duration: 4 weeks
The decision:
- Coverage: $100,000 (low risk, healthy)
- Deductible: $1,000 (they probably won’t use it, save on premiums)
Cost: $95/month × 12 months = $1,140/year
What happens if they get sick:
- Minor issue (ER visit, $2,000 bill):
- You pay: $1,000 deductible
- Insurance pays: $1,000
- Major issue (hospital stay, $80,000 bill):
- You pay: $1,000 deductible
- Insurance pays: $79,000 (under $100k limit, fully covered)
Result: Safe and affordable for healthy parents
Scenario 2: Parent With Pre-existing Condition, 6-Month Visit
Parents: Dad (68, stable diabetes), Mom (66, healthy) | Visit duration: 6 months
The decision:
- Coverage: $150,000 (safer, dad has diabetes)
- Deductible: $500 (dad likely to use healthcare)
Cost: $140/month × 12 months = $1,680/year
What happens:
- Dad gets diabetic foot infection, needs antibiotics:
- You pay: $500 deductible
- Insurance pays: $2,500 (fully covered)
- Dad develops kidney issue (diabetes-related), needs specialist visits:
- You pay: $0 (already paid deductible)
- Insurance pays: Full cost
Result: Peace of mind for a parent with health concerns
Scenario 3: Aging Parents, 1-Year Visit, Multiple Health Issues
Parents: Dad (78, hypertension + arthritis), Mom (76, asthma) | Visit duration: 1 year
The decision:
- Coverage: $200,000 (maximum protection, aging + conditions)
- Deductible: $500 (high chance of using healthcare)
Cost: $180/month × 12 months = $2,160/year
What happens:
- Mom has asthma attack, hospitalized:
- You pay: $500 deductible
- Insurance pays: $25,000 (hospitalization covered)
- Dad falls, breaks hip, needs surgery + rehab:
- You pay: $0 (already paid deductible)
- Insurance pays: $120,000 (surgery + rehab covered)
Result: Protected against serious emergencies; premium pays for itself if even one major issue occurs
The Real Cost Comparison
Here’s a side-by-side table so you can see pricing:
| Coverage | Deductible | Monthly | Annual | Best For |
|---|---|---|---|---|
| $100k | $1,000 | $95 | $1,140 | Healthy, short visits |
| $100k | $500 | $115 | $1,380 | Healthy, want peace of mind |
| $150k | $1,000 | $110 | $1,320 | Moderate health, balanced cost |
| $150k | $500 | $135 | $1,620 | Pre-existing conditions |
| $200k | $500 | $165 | $1,980 | Serious health conditions |
| $200k | $0 | $195 | $2,340 | Maximum protection |
(Pricing varies by provider and parent age; examples are for 65-year-old)
How to Make Your Decision
Ask yourself these questions:
1. How healthy are my parents?
- Very healthy → $100k coverage, higher deductible
- Some health issues → $150k coverage, lower deductible
- Multiple conditions → $200k coverage, low/no deductible
2. How long will they visit?
- 1–3 months → $100k is usually enough
- 4–8 months → $150k recommended
- 9–12 months → $150k–$200k recommended (more time = more risk)
3. Can I afford the deductible if needed?
- Yes, easily → Lower deductible (more peace of mind)
- Maybe → Higher deductible (lower premium cost)
- No → Lower deductible (avoid large surprise bills)
4. What’s my risk tolerance?
- Play it safe → Higher coverage, lower deductible
- Comfortable with risk → Lower coverage, higher deductible
The Truth: What Most Families Actually Choose
After issuing 200+ Super Visa policies, here’s what I see:
- 70% of families choose: $150,000 coverage + $500 deductible
- Why? It’s the sweet spot—affordable but protective
- 20% choose: $100,000 coverage + $1,000 deductible
- Why? Budget-conscious, young healthy parents, short visits
- 10% choose: $200,000 coverage + $500 deductible
- Why? Serious health conditions, peace of mind, longer visits
Most families regret choosing too little coverage or too high deductible. Very few regret choosing more protection.
What Happens If You Need Emergency Care
Here’s the real-world scenario:
Your mom gets a urinary tract infection that turns into kidney infection. The ER visit costs $3,000, and she needs hospitalization for 3 days (total $15,000).
With $100k coverage + $1,000 deductible:
- You pay: $1,000
- Insurance pays: $14,000
- Total covered: $15,000 ✅
With $150k coverage + $500 deductible:
- You pay: $500
- Insurance pays: $14,500
- Total covered: $15,000 ✅
- You save: $500 in out-of-pocket costs
That $500 difference is worth it for most families.
Don’t Overthink This: Get Expert Guidance
Here’s what happens when families try to figure this out alone:
- They get 3 different quotes with 3 different recommendations
- They pick the cheapest option (then regret it if something happens)
- They pick the most expensive option (then regret overpaying)
- They stress about making the “wrong” choice
Here’s the better way:
Tell me about your parents’ health, age, and how long they’re visiting. I’ll recommend the right combination of coverage and deductible, show you 3 options (budget, recommended, premium), and explain exactly why each one makes sense.
Most families feel relieved once someone who’s done this 200+ times shows them the options. The decision becomes obvious.
Next Steps: Get Your Personalized Recommendation
Coverage limits and deductibles aren’t one-size-fits-all. Your parents’ specific situation—their age, health, and visit length—determines the right plan.
Chat with me on WhatsApp with your parents’ details and I’ll recommend the perfect coverage + deductible combination. I’ll show you the actual cost, explain why that’s the right choice, and answer any questions.
Most families are surprised how affordable the right protection is once they see the full picture.